
Don’t Let Closing Costs Catch You Off Guard: Smart Strategies for Sellers
Don’t let closing costs catch you off guard—learn smart strategies for sellers to reduce expenses, avoid surprises, and walk away with more cash from your home sale.
Don’t Let Closing Costs Catch You Off Guard
Selling a house isn’t just about finding the right buyer—it’s about making smart financial decisions from start to finish. And if there’s one area where most sellers get blindsided, it’s closing costs. Don’t let closing costs catch you off guard—because if you're not prepared, these final expenses can eat into your profits more than you expect.
In this guide, we’ll walk you through everything you need to know, from understanding what these costs are to smart strategies that can save you thousands. Let’s make sure you walk away from your sale smiling—not shocked.
What Are Closing Costs for Sellers?
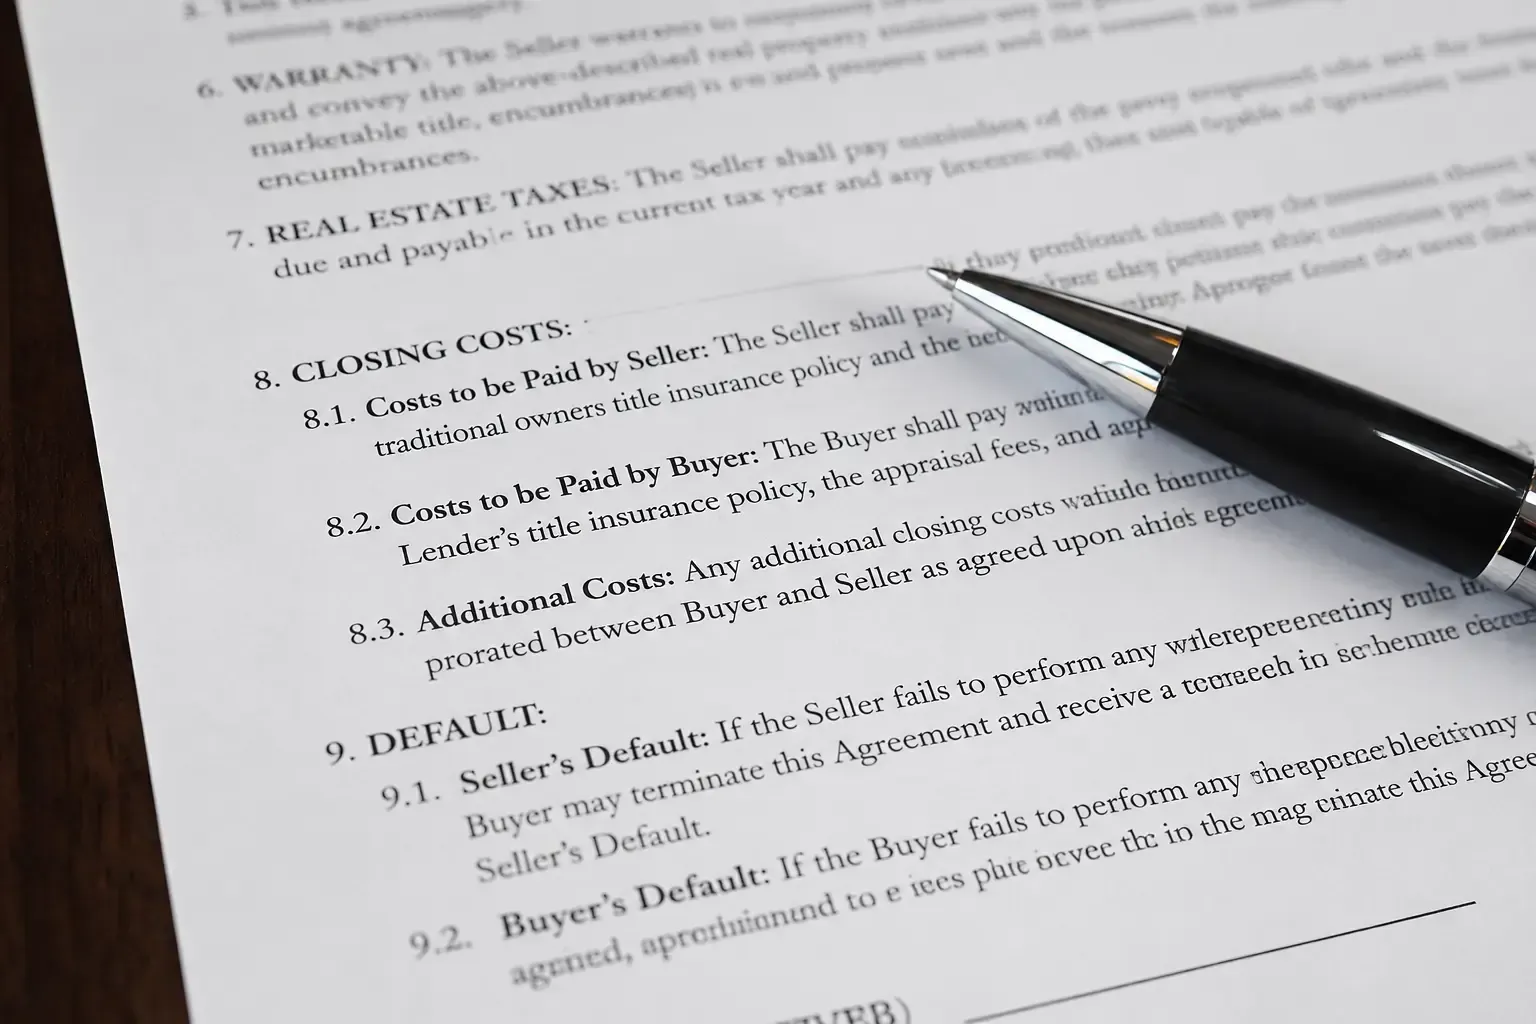
Closing costs are the fees and expenses that come with finalizing a home sale. While buyers often pay a significant chunk, sellers aren’t off the hook. These costs typically range from 6% to 10% of the home’s sale price, depending on your location and specific deal.
Here’s what usually gets lumped into closing costs:
- Real estate agent commissions
- Title insurance fees
- Escrow fees
- Attorney fees (in some states)
- Property taxes (prorated)
- Home warranties (if offered)
- HOA transfer fees
- Transfer taxes
It’s crucial to factor in these costs before setting your asking price so you can avoid last-minute financial surprises.
Common Misconceptions About Closing Costs
Many sellers walk into the process with a few myths rattling around their heads:
- “Buyers pay all the closing costs.” Nope—sellers are on the hook for several major fees.
- “I can just subtract closing costs from the buyer’s offer.” That’s risky. If the offer is low, you might end up with much less than you expected.
- “I’ll get all the money from the sale at closing.” Not true—you’ll only get the net proceeds after all the costs are deducted.
Being realistic is your first defense against disappointment.
Itemized Breakdown of Typical Seller Closing Costs
Understanding where every dollar goes helps you stay in control. Here's a typical breakdown:
Cost Item Estimated Amount
Agent Commission (5–6%) $15,000 on a $300K home
Title Insurance $1,000 – $2,000
Escrow & Settlement Fees $500 – $1,500
Transfer Taxes Varies by state (0.1–1%)
HOA Transfer Fee $100 – $500
Property Taxes Prorated based on closing date
Home Warranty $300 – $600 (if offered)
Taxes, Fees, and Agent Commissions Explained
Let’s take a closer look at some of these:
- Agent Commissions: Usually the largest cost. You pay both your listing agent and the buyer’s agent.
- Transfer Taxes: These vary widely by location but can be significant.
- Title Insurance: Protects the buyer—and it’s usually the seller who pays in some states.
- HOA Fees: If you’re in a managed community, these are often non-negotiable.
It’s important to ask for a seller net sheet early in the process to understand how these costs will affect your bottom line.
Hidden Costs That Often Surprise Home Sellers
Beyond the standard line items, here are a few sneaky charges that can creep in:
- Loan payoff fees
- Mortgage prepayment penalties
- Repairs requested after inspection
- Unpaid utility bills
- Document courier and wire transfer fees
These might seem minor individually, but collectively they can add up to thousands. Being proactive helps prevent these from blindsiding you.
How to Estimate Closing Costs Before Listing
Want to stay in control? Start with a solid estimate. Use these tools and tactics:
- Ask your Realtor for a detailed seller net sheet.
- Use online calculators with your estimated sale price and location.
- Review your mortgage payoff balance so you know exactly what you’ll owe.
Planning ahead ensures you price your home with your net proceeds in mind—not just the market value.
Working With a Professional Realtor Can Save You Money
Trying to DIY a home sale might seem like a way to save money, but it can backfire—big time. A seasoned Realtor can:
- Negotiate better deals
- Handle closing paperwork
- Recommend the right vendors
- Help you avoid legal or contractual pitfalls
In short, they pay for themselves by protecting your profit.
Proven Ways to Reduce Seller Closing Costs
Want to keep more money in your pocket? Try these:
- Negotiate commission rates with your listing agent.
- Shop around for title services.
- Limit home warranty offerings unless necessary.
- Ask buyers to cover some of the closing costs—especially in a seller’s market.
Every dollar you save in closing costs is a dollar you keep.

Negotiating With Buyers to Cover Some Costs
This is more common than you might think. In competitive markets, buyers are often willing to sweeten the deal by:
- Covering title fees
- Paying for their own insurance and appraisal costs
- Agreeing to skip certain inspection requests
A good negotiator (your Realtor) makes all the difference here.
Choosing the Right Time to Sell to Minimize Expenses
Timing is everything. Here’s why:
- Spring and summer usually mean higher prices and more leverage.
- Selling early in the year may reduce your property tax liability.
- Avoiding major holidays can help speed up closing and reduce holding costs.
The right timing helps you net more with less stress.
Using Online Calculators and Tools to Plan Ahead
You don’t need to be a financial expert—just use the right tools:
- Seller net calculators
- Tax estimators
- Repair cost estimators
Plug in your numbers and you’ll have a rough idea of what to expect before you even list.
Budgeting for Pre-Listing Repairs and Staging
Some costs hit before you even find a buyer:
- Fixing up small repairs
- Painting and landscaping
- Professional staging or photography
Create a separate budget for these so they don’t sneak up on you and delay your listing.
How to Maximize Net Proceeds from Your Home Sale
Your net proceeds = sale price - closing costs - mortgage payoff. Want to boost that number?
- Price competitively, not too high or low
- Minimize unnecessary spending
- Time the market wisely
- Choose offers with fewer contingencies
Every decision you make along the way affects this final figure.
Avoiding Last-Minute Surprises at the Closing Table
Nothing’s worse than thinking you’re all set—only to find a costly surprise at closing. To avoid this:
- Review your closing disclosure early
- Double-check title reports and payoffs
- Ask your agent to review all final statements
Being vigilant pays off. Literally.
How Capital Gains Tax Can Affect Your Final Profit
If your home has appreciated significantly, you could owe capital gains tax. But:
- If you’ve lived in the home 2 of the last 5 years, you may be eligible for a $250K (single) or $500K (married) exemption.
- Talk to a tax advisor before closing.
Taxes aren’t always part of “closing costs,” but they impact what ends up in your bank account.
State and Local Laws That Impact Closing Costs
Some states require sellers to cover:
- Title insurance
- Transfer taxes
- Attorney fees
Local regulations can change quickly, so it’s essential to work with someone familiar with your area. Your Realtor should be on top of this.
How to Get Tailored Advice for Your Property
Every sale is different. Factors like:
- Local market trends
- Property type
- Timeline for selling
All affect closing costs. Don’t guess—get expert advice from the Contact team.
Real Stories: Sellers Who Saved Thousands
- One seller avoided $3,000 in repair credits by offering a pre-inspection report.
- Another negotiated the buyer to cover $5,000 in title and escrow costs.
- A couple selling in Las Vegas timed their sale in peak season and walked away with 8% more than expected.
It happens all the time—when you’re smart and strategic.
FAQs
What percentage of the sale price do sellers usually pay in closing costs?
Usually between
6% and 10%, depending on location, agent fees, and taxes.
Can I negotiate closing costs with the buyer?
Absolutely. Especially in competitive markets, buyers may be open to splitting or covering costs.
What’s the biggest closing cost for sellers?
Typically, it’s the
real estate agent commission, often around 5–6% of the sale price.
Are there any closing costs I can avoid entirely?
Some costs, like optional home warranties or unnecessary repairs, can be skipped. Others, like taxes, are mandatory.
Should I hire a Realtor to help with closing costs?
Yes—a professional
Realtor can help reduce costs and increase your net profit.
What if I can’t afford the closing costs?
You may be able to negotiate with the buyer, offer concessions, or use part of your home equity to cover them.
Conclusion: Selling Smart Means Planning Ahead
Don’t let closing costs catch you off guard. With the right knowledge and smart strategies, you can protect your profit and avoid financial surprises. Whether it’s working with a trusted Realtor, planning your timeline, or negotiating like a pro—every step you take can make a big difference at the closing table.
Need expert help? Reach out through the Contact page today and get guidance tailored to your home and goals.
Links